TL; DR
If you are an employer or an employee in India, you might understand the importance of payroll deductions. They are statutory deductions and fall under central and state laws, which means they are non-negotiable. There are 5 buckets of payroll deductions: EPF, ESI, Professional Tax, Labour Welfare Fund, and TDS. This blog breaks down every deduction and current rates.
Every payroll cycle in India comes with the same question from HR and finance teams: which deductions apply, and to whom? The answer isn’t uniform.
A company running payroll across Maharashtra, Karnataka, and Tamil Nadu calculates several sets of numbers because Professional Tax slabs, Labour Welfare Fund rates, and even ESI thresholds can shift depending on where an employee is based.
Plus, because PF, ESI and TDS are governed by central law and PT and LWF are state subjects, it becomes easy for even experienced HR to see why payroll deductions in India trip up.
This guide walks through every deduction an Indian employer needs to track, and employees should be aware of. Whether you’re setting up payroll for the first time or auditing an existing process, this blog covers everything in detail.
What are payroll deductions in India?
Payroll deductions in India are the statutory and structural amounts subtracted from an employee’s gross salary. They are set by central Acts, state Acts, and, for gratuity and bonus, by service tenure and company performance.
Every employer in India must mandatorily calculate these amounts correctly. Miscalculation can lead to serious legal and financial problems during an audit.
An HR or payroll team managing employees across more than one state has to track all of these at once, because the central deductions are uniform nationwide while the state ones are not.
Types of payroll deductions in India
1. Statutory deductions:
Tax Deducted at Source (TDS):
TDS is income tax that the employer deducts every month from the employee’s annual income. While the selection of tax regime is important, the new tax regime is now the default. Employees must actively opt for the old regime to claim HRA and Section 80C deductions. Income up to ₹4,00,000 is tax-free, and the standard deduction is ₹75,000 under the new tax regime.
Employees’ Provident Fund (EPF):
EPF is a retirement savings scheme where both the employer and the employee contribute 12% of basic salary plus DA. On the employer’s side, 3.67% from the employer’s side goes into the EPF account, and 8.33% from the employee’s side goes into the Employees’ Pension Scheme (EPS). This is subject to the wage ceiling.
Employees State Insurance (ESI):
ESI provides medical and monetary benefits. Employees earning up to ₹21,000 per month are mandatorily covered under ESI. It covers medical care, maternity benefit, and disability compensation for eligible workers and their dependents. The employee contributes 0.75%, and the employer contributes 3.25%.
This is a state-level deduction on salaried income. PT is capped at ₹2,500 a year. Presently, it is levied in 19 states and 1 UT. States and UTs where it is not levied are Arunachal Pradesh, Chhattisgarh, Delhi, Goa, Haryana, Himachal Pradesh, Rajasthan, Uttar Pradesh, Uttarakhand, Andaman and Nicobar Islands, and Chandigarh. Every state and UT sets its own amount and makes deductions accordingly.
Labour Welfare Fund (LWF):
LWF is a state-specific contribution that funds welfare measures for workers. It is a fixed yet small amount, and it is enacted separately by each state. Only some states levy it, and the frequency varies.
2. Non-statutory deductions:
Company accommodations & amenities:
When a company provides housing, hostel stay, or a company vehicle, the cost is deducted from salary as per the agreed terms. The amount is fixed in the offer letter or a separate policy document.
Some perks come with a cost-sharing clause – canteen meals, gym memberships, or transport are common examples. The employee’s share is deducted monthly, usually at a subsidised rate set by the company.
Advance or loan repayments:
If an employee takes a salary advance or a company loan, repayment is deducted in fixed monthly installments. The schedule and amount are agreed upon in writing before the first deduction.
Cooperative societies & union fees:
Employees who are part of a workplace cooperative society or a registered trade union may have membership fees deducted directly from their salary, based on their written consent.
Voluntary insurance premiums:
Employees can opt for insurance policies voluntarily. The premium is deducted monthly or annually, depending on the terms and conditions of the policies the employee has opted for.
Labour welfare fund: State-wise contribution rates
| State/UT | Employee share | Employer share | Frequency/cycle |
|---|
| Maharashtra | ₹25 | ₹75 | Half-yearly (June/ December) |
| Gujarat | ₹6 | ₹12 | Half-yearly (June/ December) |
| Karnataka | ₹50 | ₹100 | Annual |
| Tamil Nadu | ₹10 | ₹20 | Annual |
| Andhra Pradesh | ₹30 | ₹60 | Annual |
| Telangana | ₹2 | ₹5 | Annual |
| West Bengal | ₹3 | ₹30 | Half-yearly |
| Madhya Pradesh | ₹10 | ₹20 | Half-yearly |
| Chhattisgarh | ₹15 | ₹45 | Half-yearly |
| Kerala | ₹50 | ₹50 | Monthly |
| Goa | ₹60 | ₹180 | Half-yearly |
| Haryana | ₹34 | ₹68 | Monthly |
| Punjab | ₹5 | ₹20 | Monthly |
| Delhi | ₹0.75 | ₹2.25 | Half-yearly |
| Odisha | ₹20 | ₹40 | Half-yearly |
| Chandigarh | ₹5 | ₹20 | Monthly |
Note: The respective rates are for 2026. However, rates change periodically. Hence, please confirm with the state board before filing.
Keep all your payroll deductions accurate!
Manage statutory deductions and state-specific rates without manual calculations
LWF worked example
Let’s understand how the deduction works. Take an example of an employee who works in Maharashtra. He has an annual CTC of ₹8,00,000, with basic salary set at ₹26,667 a month and gross monthly salary of ₹55,467.
- EPF: 12% of basic = ₹3,200/month
- ESI: Not applicable. Gross salary is above the ₹21,000 ceiling.
- Professional Tax: Up to ₹200/month.
- LWF: ₹25 deducted in June and December only.
- TDS: Calculated monthly based on projected annual tax liability under the employee’s chosen regime.
Common mistakes in payroll deductions compliance
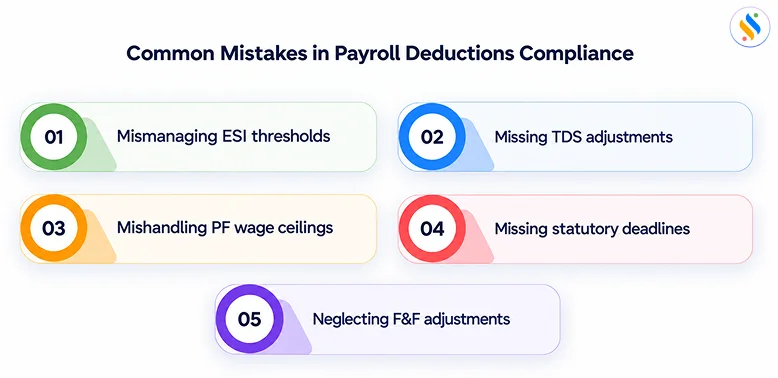
1. Mismanaging ESI mid-period thresholds:
An employee’s ESI eligibility is fixed at the start of a contribution period, even if their salary crosses ₹21,000 partway through. Many payroll teams stop the deduction the moment the raise takes effect, which is wrong.
2. Failing TDS slab and regime adjustments:
TDS is calculated on projected annual income. This way, a mid-year salary hike, bonus, or regime change should update the monthly deduction for the rest of the year. Skipping this recalculation leads to a large shortfall that shows up only at the time of Form 16.
3. Mishandling PF wage ceilings and components:
PF is calculated on basic salary + DA. Some payroll teams include allowances that should be excluded, or apply the ₹15,000 wage ceiling incorrectly for employees who were already PF members before crossing it, resulting in either short deposits or unnecessary over-deduction.
4. Missing statutory deposit deadlines:
PF and ESI are due by the 15th of the following month, and TDS is due by the 7th. Treating all three as one deadline, or filing late even by a few days, triggers interest and, for PF, disallows the deduction as a business expense.
5. Neglecting F&F exit adjustments:
Full-and-final settlement has to account for unpaid LOP, pending PF and gratuity dues, leave encashment, and any bonus owed up to the last working day. Missing one of these creates disputes and delayed settlements.
How does payroll software handle multi-state payroll deductions for Indian businesses?
There are several reasons why good payroll software becomes an effective solution for Indian businesses when it comes to managing multi-state payroll deductions.
To start with, the platform stores each state’s EPF and ESI thresholds, Professional Tax slabs, and Labour Welfare Fund rates and frequencies in one system and applies the correct one automatically.
Instead of checking it manually, the software reads everything and calculates the deductions.
This matters most for companies with employees spread across several states. A well-built system keeps three things in sync: the rate table, the filing calendar, and the payslip itself.
Comparing tools for statutory deductions? Read our guide: How to choose payroll software.
Conclusion
We hope that through this blog, you have gotten all the insights on payroll deductions in India and how they work. Between statutory and non-statutory deductions, an Indian payslip carries essential components that most HR teams have time to track manually. Whether it is about adding multi-state operations or switching tax regime mid-year, the room for error keeps expanding when important things get done manually. This is where the mistakes we talked about tend to happen.
Getting payroll deductions right consistently is all about having a system that applies the correct rule every single month, for every employee.
It is for this reason that Super Payroll, a module by Superworks, has been built. From EPF and ESI to state-specific LWF and PT, the platform calculates everything automatically without the need to recheck manually, eventually saving the time of HR and payroll teams. Book a demo now!