TL; DR
When you talk about salary components in India, it falls into four groups. Employees often find themselves struggling to understand the deductions in their payslips. This leads to frequent back-and-forth with HR and top management. Conversely, if there is clarity, it will simply boost employees’ trust because there is transparency. This blog focuses on explaining the components of salary that every Indian employer and employee should be aware of. In addition to this, they should also take cognisance of the new reforms announced by the state and central governments, respectively.
In India, a salary is not merely a figure.
What appears as a single figure in an offer letter or payslip is usually made up of several salary components. Each has a different purpose.
Basic salary, HRA, DA, special allowances, bonuses, contributions, deductions – all these form the overall compensation of the employee.
The way these components are structured can affect take-home pay, tax treatment, statutory contributions, and the employer’s payroll calculations.
Now, don’t be under the impression that all components are rigid. Both governments – central and state keep announcing reforms and updates in the laws. The recent ones are the announcements of four new labour codes and the EPF wage hike that took place some time ago.
For employees, understanding the components of salary in India can make it easier to understand their take-home pay. For HR, getting these components right is essential for smooth payroll processing and compliance.
So, what are the salary structure components, and how does each one affect an employee’s pay?
In this blog, we’ll cover all that and more.
What are the salary components in India?
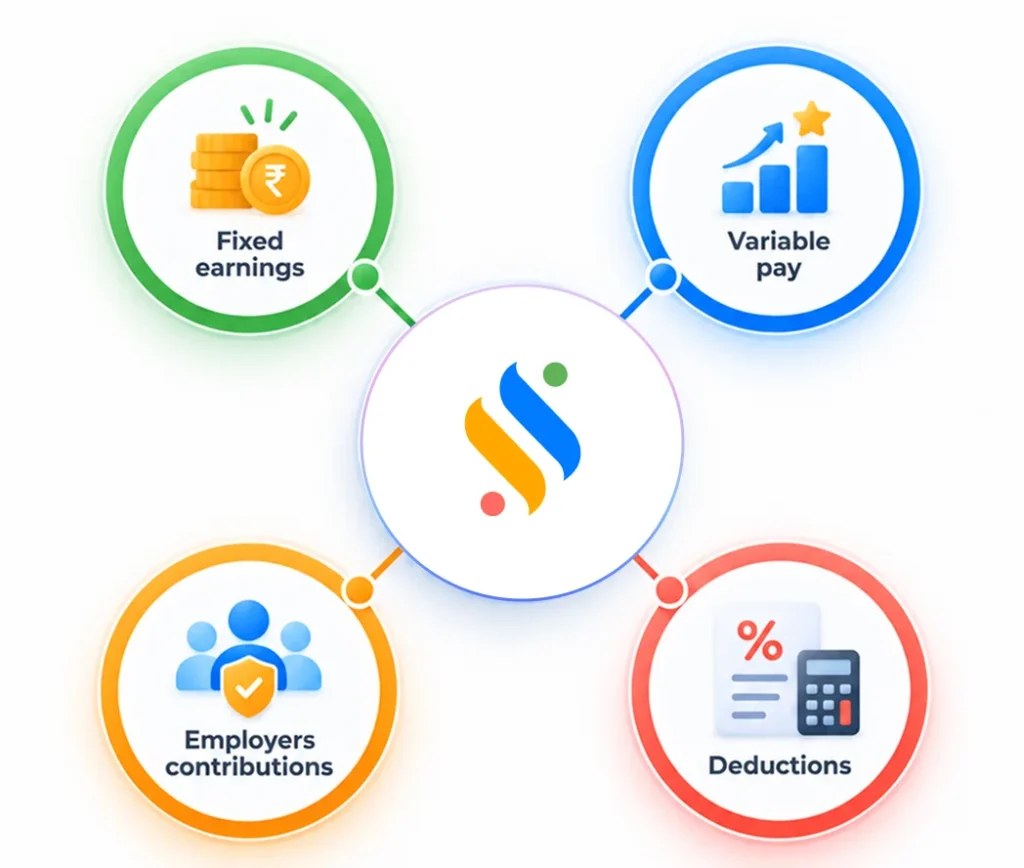
An employee’s compensation package in India is broadly structured around CTC(Cost to Company). CTC represents the total amount an employer spends on an employee annually. All the salary components are divided into 4 groups: fixed earnings, allowances, statutory contributions, and deductions.
| Groups | Components | Paid to and when | In CTC? |
|---|
| Fixed earnings | Basic, dearness allowance, HRA, special allowance, conveyance, meal allowance | Employee, every month | Yes |
| Variable pay | Statutory bonus, performance bonus, incentives, overtime | Employee, when earned | Usually, if budgeted in the offer |
| Employer contributions | Employer PF, EPS, EDLI, ESI, gratuity, group insurance | PF office, ESIC, or insurer. Gratuity is held as a provision | Yes |
| Deductions | Employee PF, employee ESI, professional tax, TDS | Withheld from pay and sent to the PF office, ESIC, the state, or the tax department | Already counted in gross pay |
Fixed earnings:
Fixed earnings are the base of the salary. Basic salary is the largest fixed component. It is the base for PF, gratuity, and the HRA exemption, so it drives both pay and employer cost. DA adjusts pay for the rising cost of living.
1. Allowances:
Allowances are extra monthly payments. They cover specific costs or balance the structure. All of them are taxable unless an exemption applies.
1. HRA (House rent allowance):
Part of it is exempt under the old tax regime. The exempt amount is the lowest of the actual HRA, rent paid minus 10% of salary, and 50% of salary in eight cities (Delhi, Mumbai, Kolkata, Chennai, Bengaluru, Hyderabad, Pune, and Ahmedabad). HRA is fully taxable under the new regime.
2. Special allowance:
This is the balancing figure that brings the structure up to the full CTC. It is fully taxable.
3. Conveyance allowance:
Under the new regime, it is generally taxable.
4. Meal allowance:
Employer-provided meals are tax-free up to ₹200 per meal.
Allowances also have a legal limit. If they go above 50% of total remuneration, the excess is added back to wages.
2. Statutory contributions:
Statutory contributions are amounts the employer pays under law. They count toward CTC, but the employee does not receive them in hand each month.
1. Employer PF:
The employer pays 12% of wages. Of this, 3.67% goes to the employee’s EPF account, and 8.33% goes to the EPS. The employer also pays 0.5% for EDLI insurance and 0.5% in admin charges.
2. Employer ESI:
The employer pays 3.25% of gross pay. This applies only if gross pay is ₹21,000 a month or less.
3.Gratuity:
The employer sets aside about 4.81% of basic pay each month. It is paid after five years of continuous service. Fixed-term employees qualify after one year under the new code. The formula is last drawn basic and DA × 15 × years of service/ 26.
3. Deductions:
Deductions are amounts taken out of gross pay before the employee is paid. They reduce take-home salary.
- Employee PF: 12% of wages, on the same ceiling as above.
- Employee ESI: 0.75% of gross pay, only for employees within the ₹21,000 limit.
- PT: Charged by the state. It is capped at ₹2,500.
- TDS: The new regime is the default, with a ₹75,000 standard deduction. The old regime allows ₹50,000.
- LWF: A small contribution under each state’s Labour Welfare Fund Act. It funds welfare schemes for workers. Both the employee and the employer pay. The employee’s share is a deduction, and the employer’s share is an extra cost.
Deductions affect what reaches the bank account.
From salary structure to payslip generation, manage everything from one place!
Automate salary calculations and deductions while keeping every payroll cycle accurate and transparent
New changes that every HR and payroll team should be aware of
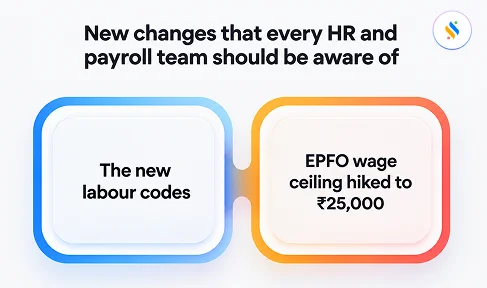
Two changes affect how you build and run salaries right now: the new labour codes and the higher EPF wage ceiling. Both change what you pay, deduct, and set aside.
1. The new labour codes:
The government brought the four labour codes into force on 21st November 2025. They merge 29 older laws into four: the Code on Wages, the Code on Social Security, the Industrial Relations Code, and the Occupational Safety, Health and Working Conditions Code. Here is what changes for salary components in India:
1. Definition of wages:
Wages now mean basic pay, DA, and retaining allowance. This applies across all four codes.
2. The 50% rule:
Wages must be at least 50% of total remuneration. If allowances go above, the excess is added back to wages.
3. A higher base for many payments:
PF, gratuity, bonus, overtime, and leave encashment are calculated on wages. When basic rises, all of them rise.
4. Gratuity for fixed-term employees:
They now qualify after one year of service, down from five.
Companies that kept basic at 30–35% of pay will see higher PF and gratuity costs. Employees may see lower take-home pay but a larger retirement balance.
2. EPF wage ceiling raised to ₹25,000:
The government has raised the EPF wage ceiling from ₹15,000 to ₹25,000 a month. The change took effect on 17th September 2026. The contribution rates stay the same at 12% for the employee and 12% for the employer. Only the wage base on which mandatory contributions apply has changed.
| Contribution at the ceiling | Old ceiling (₹15,000) | New ceiling (₹25,000) |
|---|
| Employee PF (12%) | ₹1,800 | ₹3,000 |
| Employer EPF (3.67%) | ₹550 | ₹917 |
| Employer EPS (8.33%) | ₹1,250 | ₹2,083 |
| Employer EDLI (0.5%) | ₹75 | ₹125 |
The new ceiling applies from 17th September, so many payroll teams apply ₹15,000 for 1–16 September and ₹25,000 for 17–30 September.
Points to note:
- Those with wages between ₹15,001 and ₹25,000 may now come under mandatory coverage, subject to the applicable scheme rules.
- The EPS share is calculated up to the ceiling, so more of the employer contribution moves into the pension scheme.
What to do now?
- Update the PF ceiling from ₹15,000 to ₹25,000.
- Recheck the September payroll and make sure the split-month calculation is applied.
- List affected employees. Find everyone with PF wages between ₹15,001 and ₹25,000.
- Audit the basic share. Confirm that basic + DA is at least 50% of total remuneration.
- Update gratuity provisions. Include fixed-term employees too.
- Inform your team. Show employees how the changes affect their payslip.
How can Indian businesses build a salary structure that holds up?
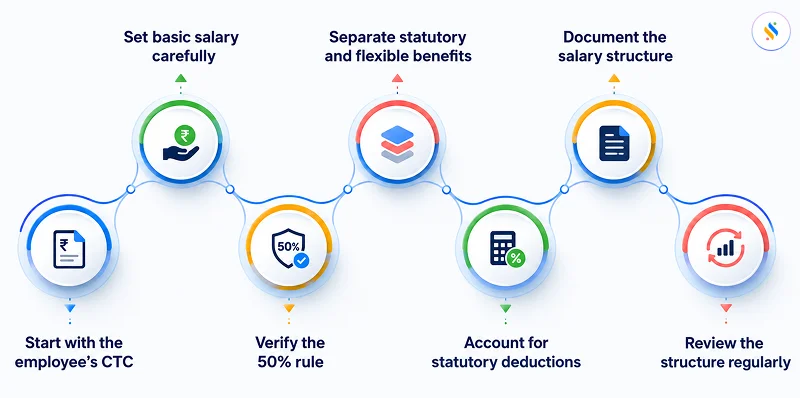
1. Start with the employee’s CTC:
Fix the total annual budget first. Then subtract the employer-side costs. What remains is the gross salary you can split into components.
2. Set basic salary carefully:
Basic is the base for everything. If it is too low, the structure fails. If it is too high, employees’ take-home pay will fall. An ideal solution here? 50% of total remuneration.
3. Verify the 50% rule:
Add basic, dearness allowance, and retaining allowance. Divide the total by the monthly remuneration. The result must be at least 50%. Run it for every salary band.
4. Separate statutory components from flexible benefits:
Statutory components follow the law and apply to every eligible employee. Flexible benefits follow your policy. Keep the two apart. Most allowances are fully taxable under the new regime.
5. Account for statutory deductions:
List every deduction against the employee’s gross pay, state, and tax regime:
- Employee PF: 12% of wages, up to the ₹25,000 ceiling or on actual basic.
- Employee ESI: 0.75%, only if gross pay is ₹21,000 a month or less.
- PT and LWF: Set by the state.
- TDS: Depends on the regime and declarations.
6. Document the structure clearly:
Create one salary template for each grade. For each component, write down the formula, eligibility, etc. The offer letter should show the CTC breakup, with employer contributions listed separately. Record your PF approach too, whether on the ceiling or on actual basic.
7. Review the structure when rules change:
Review the structure whenever a new notification arrives. Any delay here can have serious problems.
How does payroll software help you manage salary components easily?
Managing salary components in spreadsheets can be a good solution for the short term. But you should not consider it for the long term. The ever-evolving nature of compliance, reforms, and the introduction of new laws – all these are things that are impossible to track manually. Then someone must edit every formula by hand. One wrong cell can mean a wrong PF deduction and payslip. The result? An issue will arise in the audit. Payroll software is the ideal fix. You set up each component once and make necessary changes, if required. You can remain stress-free as the platform automatically updates whenever there are changes in PF, ESI, PT, LWF, and TDS. The software then applies them by grade, state, and tax regime every month. Attendance, leave, and shift data go directly into the system without any manual intervention. This means fewer errors, clearer payslips, and organized records.
Conclusion
We hope that by now you must have understood the different salary components that are present in the Indian business space. Understanding the different salary components in India helps both employees and employers. Employees will know their exact take-home pay, and employers will be able to make changes in their structure on time. The key is accurate calculation of every component and keeping structures revised whenever changes are announced. As laws continue to evolve, businesses also need a smart solution that can keep up with these changes. Super Payroll by Superworks is built for this very reason. It automates and centralizes salary components, salary calculations, statutory deductions, statutory compliance, payslip generation, etc. This way, it reduces manual work, saves the HR and payroll team’s time and helps run payroll more efficiently. Book a demo now!